Essential tactics for guarding retirement income sources today
Protect your retirement through dynamic withdrawals, cash reserves, and multiple income sources instead of relying on market returns alone.
Protect your retirement through dynamic withdrawals, cash reserves, and multiple income sources instead of relying on market returns alone.
Housing has become the largest expense category in retirement, consuming 36% of spending for those 65 and over—a burden that erodes retirement security.
Protect retirement income through dynamic withdrawal strategies, diversified sources, and tax-efficient account sequencing rather than relying on outdated single-source approaches.
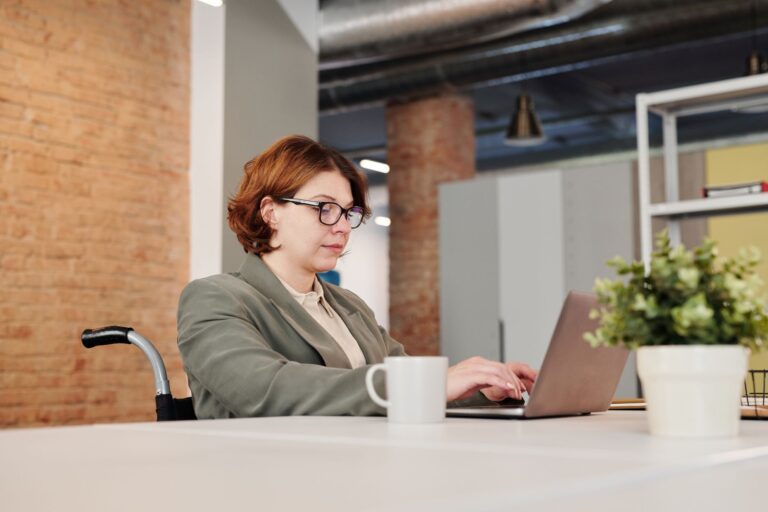
Yes, you can work while receiving disability benefits, but you must navigate specific rules and earnings limits set by Social Security.
Spousal benefits don't grow with delay, but the survivor protection from your delayed claim significantly affects your spouse's lifetime security.
Delaying Social Security to 70 doesn't increase your spouse's spousal benefit, but it permanently locks in a higher survivor benefit—the single most valuable protection for couples.
SSI recipients face an unusual July 2026 payment schedule when two deposits arrive within a single month—here's what it means for your budget.
A disability review is triggered when the Social Security Administration or a private disability insurance company examines whether you still qualify for...
SSI recipients get two payments in July 2026 due to an August 1 Saturday; there's no August payment.
Keeping your disability benefits requires ongoing vigilance, timely reporting, and understanding the rules that govern your specific program.